
Agadir's Tourism Growth Reaches New Heights
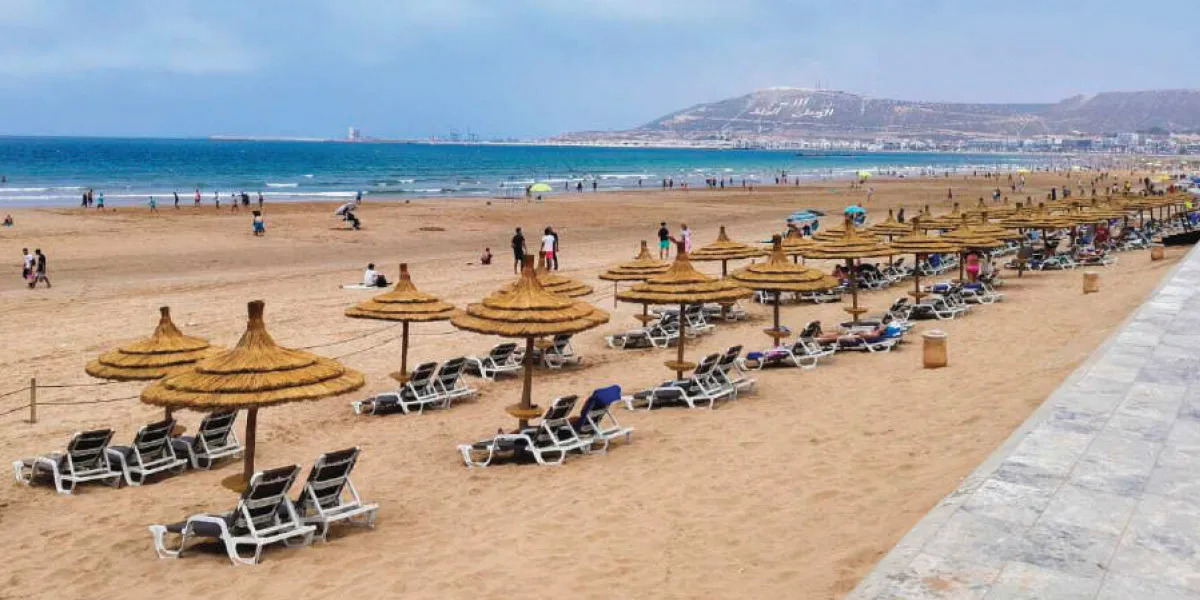
Agadir, buoyed by the strength of domestic tourism and the British market, has firmly established its growth trajectory by surpassing one million visitors by the end of August 2026, marking a notable increase of 4.59%. The destination recorded an impressive 4.6 million overnight stays, reflecting a 6.71% rise. The summer rush in August culminated in an occupancy rate of 80.34%, with arrivals increasing by 2.40% and overnight stays by 2.64% month-on-month. This surge emphasizes Agadir's appeal as a premier tourist destination.
To further bolster the French outbound market, which is ranked second in overnight stays and third in arrivals, Agadir participated in the IFTM Top Resa tourism fair. This strategic move aims to enhance the French market's contribution to local tourism, as the destination encompasses hotels in nearby Taghazout Bay, Aourir, and Imi Ouaddar. For the second consecutive year, Agadir has welcomed over one million tourists post-summer rush, as highlighted in the latest tourism analysis from the Agadir Souss-Massa Regional Tourism Council (CRT). The data confirms a consistent upward trend, with overall arrivals increasing by 4.59% and hotel stays by 6.71% during the first eight months of the year.
In detail, the total number of tourist arrivals reached 1,059,271 visitors, compared to 1,012,787 during the same period in 2025, resulting in an additional 46,484 arrivals. Moreover, the volume of overnight stays exhibited a significant growth, reaching 4,596,582 compared to 4,307,731 the previous year, which translates to an increase of 288,851 overnight stays. This overall performance is accompanied by an improvement in the average length of stay (DMS), which rose from 4.25 days in 2025 to 4.34 days, indicating the destination's enhanced ability to attract and retain tourists through its diverse activities.
Domestic Market Dominates Visitor Numbers
The analysis of market structures reveals several dynamics, particularly regarding the domestic tourism market, which remains the leading source of visitors with 332,183 arrivals (up 4.54%) and 945,263 overnight stays (up 3.50%). This segment alone accounts for 31.36% of total arrivals and 20.56% of overall overnight stays, despite a shorter average length of stay of 2.85 days. On the international front, the British market stands out as a key driver of growth, leading in terms of overnight stays with 246,431 arrivals (up 6.29%) and generating 1,429,595 overnight stays (up 9.67%), which constitutes 31.10% of total stays with an exceptionally high DMS of 5.80 days.
Conversely, the French market, while retaining its second position in terms of overnight stays with 900,211 units (up 2.02%), saw a slight decline in visitor numbers to 180,719 tourists (down 3.77%, or 7,071 fewer visitors). This decline underscores the need for the promotional push initiated at IFTM Top Resa. A noteworthy development has been the Polish market's emergence as a growth driver, witnessing a staggering 43.30% increase in arrivals (from 45,549 to 65,271) and a 40.88% rise in overnight stays (from 179,123 to 252,345), capturing 6.16% of total arrivals for the destination.
Germany has also solidified its position with 46,902 arrivals (up 2.41%) and 268,650 overnight stays (up 3.11%), while the Netherlands recorded substantial growth with a 53.27% increase in arrivals (15,865) and a 56.46% rise in overnight stays (76,963). In terms of accommodation types, five-star hotels have thrived, capturing 23.93% of arrivals (285,448) and 26.82% of overnight stays (1,407,944), with a room occupancy rate of 71.67% (up from 66.32% in 2025). Four-star hotels also remain a cornerstone of this dynamic with 259,266 arrivals (up 0.64%) and 1,203,093 overnight stays (up 0.09%), maintaining the highest occupancy rate in the sector at 79.94%. Tourist villages recorded 1,060,433 overnight stays (up 0.11%) and a 73.55% occupancy rate, while the overall weighted average occupancy rate across the entire destination reached 68.67%, reflecting a 4.16-point increase.
While Agadir's overall performance continues to soar, Taghazout Bay faced a contrasting trend in August 2026 compared to 2025. The comparison between these two destinations highlights a complementary offering but also distinct trajectories, particularly during the summer rush. Agadir City remains the central hub for tourism, accounting for 84.51% of total arrivals and 83.64% of overnight stays by the end of August 2026, up from 82.13% and 80.97% the previous year. In August, Agadir recorded 150,340 arrivals (up 5.36%) and 668,017 overnight stays (up 6.03%), driven by a rise in domestic market activity (up 8.31% in arrivals to 73,132 and up 8.86% in overnight stays to 251,009) as well as robust British tourism (up 12.52% in arrivals to 28,220 and up 7.42% in overnight stays to 172,094). In contrast, Taghazout Bay, positioned in the premium tourism segment, represented 15.49% of the total arrivals and 16.36% of overnight stays for the destination but experienced a downturn in August 2026 with an 11.21% decline in arrivals (27,559 compared to 31,038 in 2025) and an 11.76% drop in overnight stays (130,626 compared to 148,042).
This decline in Taghazout can primarily be attributed to a reduction in the domestic summer clientele, which saw 18,345 arrivals, a decrease of 4.14%, and 77,913 overnight stays, down 6.28% compared to 2025. However, this trend is only the visible tip of the iceberg, as the decline within classified accommodation units contrasts with the informal and formal rental markets, which reflect a more hidden aspect of the situation. Additionally, traditional European markets such as France and the UK also showed declines, with France experiencing a 23.32% drop in arrivals and a 21.34% decrease in overnight stays, while the UK saw a 15.49% fall in arrivals and an 18.92% drop in overnight stays.
The analysis of August 2026 confirms a peak in activity during this month, with total tourist numbers increasing by 2.40% to 177,899 compared to 173,734 in August 2025, while overnight stays rose by 2.64% to 798,643 from 778,065, yielding an additional 20,578 overnight stays. The average length of stay remained stable at 4.49 days, slightly up from 4.48 days in August 2025. The domestic market played a critical buffering role, capturing 51.42% of total arrivals for the month with 91,477 vacationers (up 5.56%) and 328,922 overnight stays (up 4.84%), followed by the British market, which totaled 31,199 arrivals (up 9.07%) and 192,878 overnight stays (up 3.78%, with a DMS of 6.18 days). Meanwhile, the French market experienced a contraction of 12.23% in arrivals (22,910) and a 7.50% decline in overnight stays (117,997), even though its average length of stay improved to 5.15 days.
From an accommodation perspective, August underscored the appeal of high-end establishments: five-star hotels attracted 43,509 guests (up 7.86%) for 221,110 overnight stays (up 10.89%), achieving a room occupancy rate of 80.52% and an overall occupancy rate of 93.66%. Four-star hotels generated 192,188 overnight stays, boasting the highest occupancy rate in the sector at 85.36%, while tourist villages recorded significant increases in arrivals (up 11.95% to 34,671) and overnight stays (up 4.09% to 179,439), achieving an occupancy rate of 84.76%. Overall, the room occupancy rate across the entire destination reached 80.34% in August 2026, up from 79.06% in 2025, with 353,567 rooms occupied out of an operational capacity of 14,196 units.
As reported by leseco.ma.