
Casablanca's Strategic Positioning in Africa's Financial Landscape
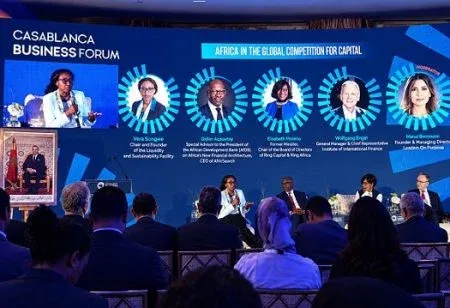
Casablanca is rapidly establishing itself as a pivotal financial hub in Africa, yet it faces significant challenges in transforming burgeoning business activities into robust capital markets and enhanced financial intermediation. Despite the continent boasting over $2.1 trillion in institutional assets, a multitude of regulatory hurdles, insufficient expertise, and a lack of market depth continue to impede the effective mobilization of these funds for investment within Africa. The discourse surrounding financial growth is progressively shifting from merely attracting foreign investments to fostering the necessary institutions and instruments that will redirect African savings into local investments. This paradigm shift was notably emphasized at the Casablanca Business Forum held on October 2, where key industry leaders, including Saïd Ibrahimi, CEO of the Casablanca Finance City Authority, articulated the need for a realignment in Africa’s financial strategies. Ibrahimi remarked, “Value chains are being reshaped, capital is being redeployed, and partnerships are diversifying,” highlighting the evolving nature of Africa’s economic landscape.
The Diverse Financial Models Across Africa
As Casablanca positions itself to capitalize on this transformation, it has made remarkable strides in the Global Financial Centres Index, ascending 11 places to secure the 38th rank globally, making it the highest-ranked financial center in Africa and third in the Middle East and Africa region, trailing only Dubai and Abu Dhabi. This ranking underscores Casablanca's burgeoning reputation as a business nexus, with the Casablanca Finance City (CFC) hosting over 300 member companies and approximately 9,400 employees, actively operating across 53 African nations. Notably, Lamia Merzouki, deputy CEO of CFC, mentioned that nearly $20 billion worth of projects in Africa are currently under the management of teams based in Casablanca. However, the complexity arises in the fact that managing a project from Casablanca does not necessarily correlate with the capital being raised, the fund being domiciled, or the transactions being executed locally. The distinction between a business hub and a financial center lies in the ability to structure, intermediate, and reallocate capital effectively.
Africa’s financial centers have evolved through different models, each presenting unique advantages and challenges. Johannesburg remains a benchmark for financial depth, characterized by substantial pension funds, insurers, and asset managers, supported by a well-developed capital market with significant domestic savings. Conversely, Mauritius has carved a niche in fund domiciliation and administration, positioning itself as a complementary partner to major financial centers rather than a direct competitor. As articulated by Sanjay Bhunjun, chairman of the Economic Development Board, Mauritius aims to attract investors seeking exposure to Africa. Emerging centers like Kigali are also beginning to establish specializations in asset management, fintech, and climate finance, while Casablanca pursues a hybrid model designed to attract financial firms, multinationals, and international advisory entities. Unlike Dubai's integrated financial ecosystem, Casablanca aims to present itself as more than just an offshore financial center driven by tax incentives; it seeks to cultivate a diverse financial environment that enhances the mobility of talent and capital.
Despite these advancements, significant gaps remain in terms of financial depth. Current statistics reveal stark contrasts: market capitalization of listed companies in South Africa is approximately 327% of its GDP, while Morocco lags behind at just 62.5%. Similarly, bank lending disparities reflect a troubling trend, with credit to the private sector representing nearly 78% of Morocco’s GDP compared to 89% in South Africa and often falling below 30% in various West African economies. Lionel Zinsou, former prime minister of Benin, succinctly states that “Finance must be treated as an industry,” underscoring the necessity for African economies to enhance their market depth and institutional frameworks.
Compounding these challenges is a paradoxical reality: while Africa possesses over $2.1 trillion in institutional assets, effectively mobilizing these funds remains a complex endeavor. Didier Acouetey, special adviser to the African Development Bank president, suggests that the focus should not solely be on acquiring new capital but on deploying existing resources more effectively. Mobilizing a mere 20% to 30% of these assets, particularly through reinforced guarantee mechanisms, could significantly enhance investment opportunities across the continent. However, this challenge transcends regulatory or financial constraints; it also encompasses a profound shortage of in-house expertise among many African pension funds, which often lack the necessary teams to evaluate infrastructure project risks or conduct thorough due diligence on unlisted investments.
For instance, Nigeria's pension regulations permit certain portfolios to allocate up to 15% of their assets to private equity, yet alternative investments remain negligible within portfolios. Thus, the imperative for African financial centers is to shift their focus from merely attracting external capital to effectively channeling domestic savings into local markets. The Casablanca Finance City is proactively collaborating with the African Development Bank to enhance financial integration and develop innovative instruments aimed at mobilizing private capital. Additionally, CFC is prioritizing the establishment of a sustainable finance specialization, particularly in carbon markets, with an ambitious goal of reaching 500 member companies by 2030.
As reported by ecofinagency.com.