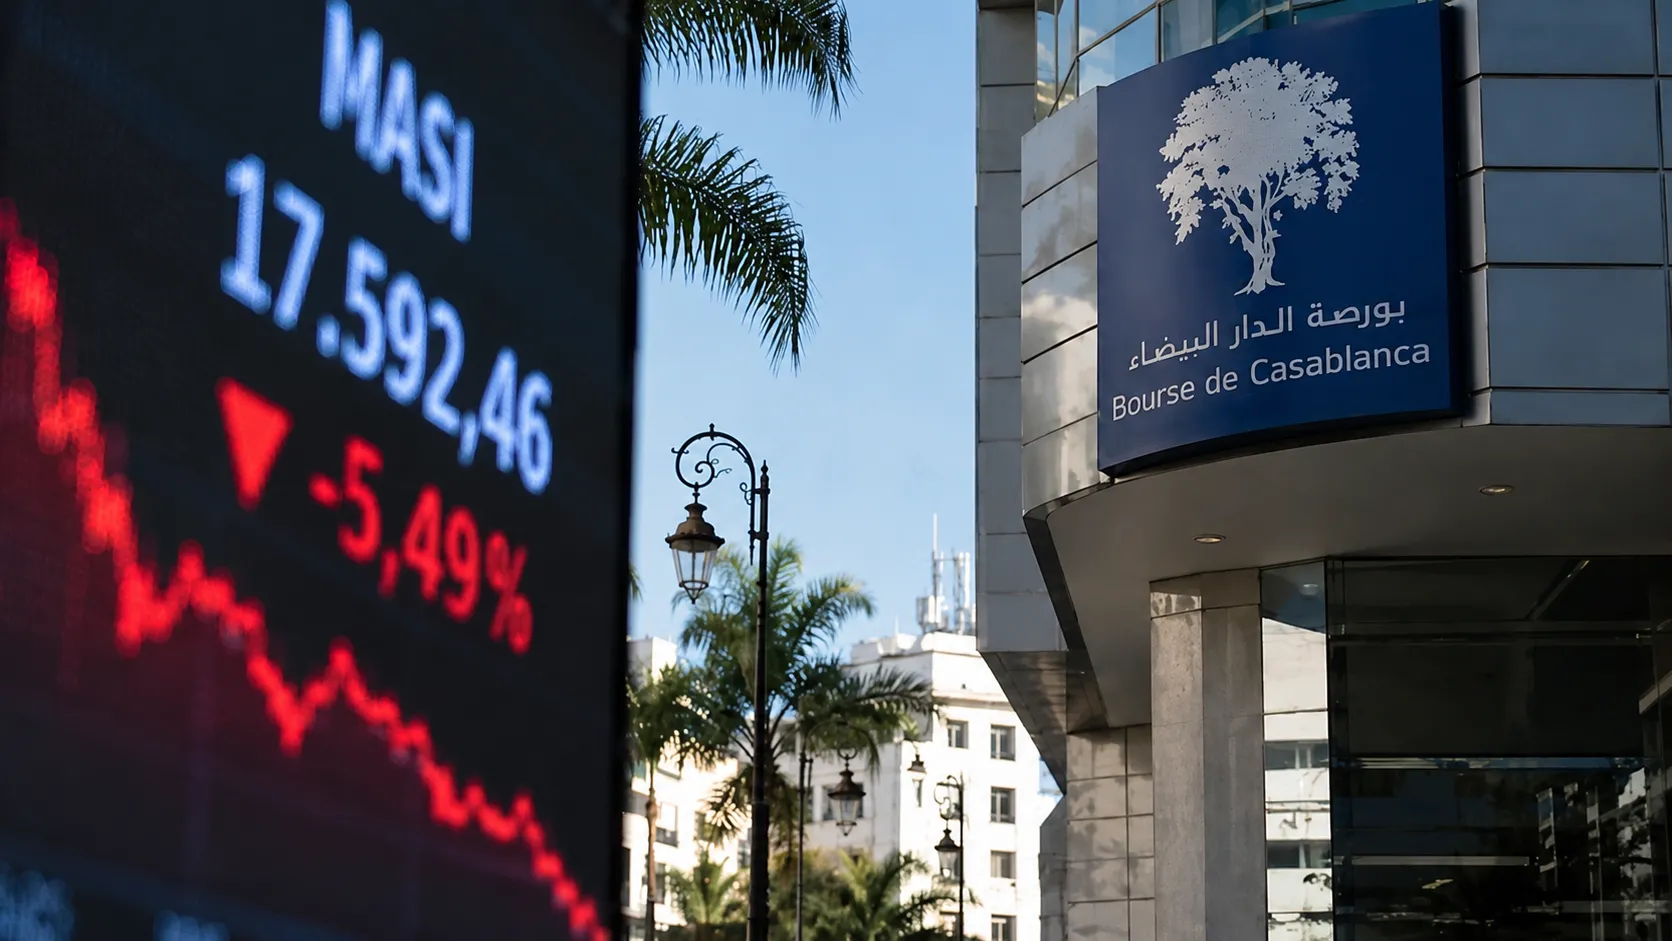

As of Sunday, September 20, 2026, the market index has experienced a significant drop of 5.49% over the week, settling at 17,592.46 points. This decline brings the total downward trajectory since the beginning of the year to 6.65%. Meanwhile, the MASI 20 index reflects an even steeper annual decrease of 13.69%. This week saw a clear trend of correction starting from Monday, with successive declines on Tuesday and Wednesday. The market faced a technical incident that led to the cancellation of Thursday’s trading session, but trading resumed on Friday, only to witness an additional drop of 2.18%.
During this tumultuous period, trading volumes have notably increased. On Friday, transactions amounted to 624 million dirhams (MDH), a substantial rise compared to 216 MDH on Wednesday and 516 MDH on Tuesday. The sales of mutual funds have intensified the selling pressure on an already weakened market, which has been grappling with several sessions of profit-taking.
The rise in bond yields has also adversely affected the stock market. In the secondary market, the five-year bonds gained over 15 basis points between September 9 and 16, the ten-year bonds increased by more than 12 basis points, and the fifteen-year bonds climbed over 13 basis points. Such a rise in bond yields enhances their relative appeal, simultaneously raising the discount rates utilized for stock valuation.
Internationally, the situation has not been favorable either. Brent crude oil prices remain above $100 amid ongoing tensions in the Middle East and supply disruptions. The increase in energy prices continues to fuel inflation fears, especially as major central banks tighten their monetary policies. For instance, the Federal Reserve raised its rates by 25 basis points this week, adjusting the range to 3.75%-4%.
From a technical standpoint, the breach below the 18,100 points mark has exacerbated the deterioration of the MASI index's configuration. The index is now navigating around the 17,500-17,600 points range, which is a critical level to monitor in the upcoming sessions.
Next week is expected to be eventful with the Bank Al-Maghrib Council meeting scheduled for Tuesday, September 22. The market is also anticipating further semi-annual earnings reports. Several results disclosed in recent days remain robust despite the declining prices, which may enhance selectivity among stocks in a market that has become significantly more demanding.
As reported by boursenews.ma.